Your advisor
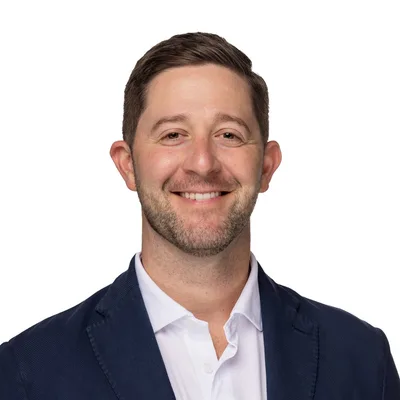
David Talley, CFP®, EA
Leads the strategy, the recommendations, and the tax planning. Every client works directly with him.
Retirement Planning
Retirement planning is financial planning, done when everything changes at once. It uses the same disciplines and a lot of the same words. What's different is the context: it's done in the middle of the largest financial event of your life, and a whole separate set of rules comes into force when it happens.
What happens first
You don't need to know what you need before the first call. Each step ends with something in your hands, and the next step is yours to take, or not.
15 minutes, by phone
About an hour
About six months
In short
Three things change at the same time, and that's what makes this phase its own kind of planning.
For decades the job of your investments was to grow. Now they have to create income, month after month, for the rest of your life. Not that they stop growing, but the question is more nuanced than it used to be: which dollars are for next spring, which are for next fall, and which have thirty more years to live. Your savings have to become a paycheck, and building that paycheck is most of what retirement planning is. How savings become a retirement paycheck.
Between your late fifties and your mid-seventies the tax law changes on you more than at any other stretch of your life. Penalty-free access to retirement accounts arrives. Social Security has a window of claiming ages, and the choice is permanent. Medicare premiums start being set by your income from two years earlier. Required distributions begin, whether you need the money or not. New deductions become available and old ones fall away. It's overlapping, it's confusing, and most of it is new to you because you've never had to use it before.
Inside that stretch sits the biggest tax decision most people ever get: the window between the last paycheck and required distributions, when income is low and a Roth conversion can move money to the tax-free side at a price that never comes back. How much to convert, and when.
You probably have more wealth right now than at any point in your life. That cuts both ways. The advantage of doing this well is bigger than it has ever been, and so is the cost of getting it wrong. A withdrawal order chosen carelessly, a conversion sized to the wrong year, a Social Security claim made early because it was available: each one is a decision that costs more here than it would have at forty. Which account pays you first. When to claim Social Security. The risk nobody talks about: a bad market in the first years.
You could say it's three things. The creation of income in retirement. Making sure you don't pay more in taxes than you have to, where the transition is from lowering next year's tax bill to lowering the cumulative amount you pay over your lifetime. And the estate planning that most people have put off, done in concert with the rest, because the account decisions and the estate decisions are the same decisions seen from two sides. How lifetime taxes get planned.
Before retirement, a lot of people can do this largely on their own. Not everyone, but a lot of people are capable of saving, investing, and doing the right things without help. Approaching retirement, enough changes at once that it's often, for the first time, truly worth hiring someone who knows what they're doing to piece it all together.
That's why this is our focus, and why the same person is a tax advisor, a financial planner, and an investment advisor. At the cusp of retirement and inside it, those three affect one another in a magnified way, and a decision made in one room without the other two in it is the most expensive kind.
The plan, the investments, and the taxes get decided together, at one table, inside The Keystone Method, over about six months. The paycheck gets designed, the conversion window gets sized, Social Security gets a date, the estate documents get done, and the portfolio is managed in accordance with the plan. Then it keeps going: Wealth Advisory manages the investments, keeps thinking about your situation all year, and brings you what you should know at the spring and fall sessions, and Tax Advisory manages the tax year so the conversion decided in October is the one on the return in April.
What it costs
After Keystone, both ongoing services are optional. Wealth Advisory is 1.00% of managed assets a year, and its fee for the year is the larger of that or $5,000. Tax Advisory is $200 a month, with the return included. The pricing page has every number.
Who you'll talk to
Your advisor
Leads the strategy, the recommendations, and the tax planning. Every client works directly with him.
Practice Manager
Keeps the experience organized and responsive between meetings, and is usually the fastest way to get something done.
In their words
67 Google reviews, count as of November 2026
Read them on Google ↗“We started working with David and his team almost 10 years ago, and I couldn't be happier with his support and advise. He genuinely cares about his clients and understands how every situation is different and often fluid as life throws curve balls when we least expect it. …”
“David and his staff have been great to work with. This last year is when I engaged him. The process he walked through to get to know me was a comfort. Understanding who I am, where I’ve been and where I want to go requires more than just reviewing financial information and he worked to learn. His staff has been outstanding in communication. I would recommend Talley Financial.”
“… We never thought we needed a financial advisor until we went and spoke with David. He has a way of explaining our finances and relieving our anxiety about money. He led us down a very sensible path. So glad we found him and would highly recommend him to anyone needing answers for their financial planning needs.”
Securities offered through Registered Representatives of Cambridge Investment Research, Inc., a broker-dealer, member FINRA/SIPC. Advisory services through Cambridge Investment Research Advisors, Inc., a Registered Investment Adviser. Cambridge and Talley Wealth are not affiliated. Cambridge does not offer tax or legal advice.
Reviews on this site may or may not be by clients of the firm. No compensation is being provided for sharing of opinions and experiences on this site. The reviewer's comments may not be representative of any other person's experience and is no guarantee of future performance or success.
An ellipsis (…) marks where a review is shortened. Every review appears in full on Google.
Before you decide
Bring the rest to the Explore Call.
Five years out is a good time, because the conversion window, the Social Security decision, and the shape of the paycheck all benefit from being designed before the last paycheck stops. It's never too late to start, but a few of the best decisions have dates attached.
Because the job changes. Growing money and creating income from it are different problems, and the tax rules that arrive in this stretch are new to almost everyone. Many people who did well on their own find this is the first time hiring help is clearly worth it.
A pension is part of the paycheck design, and if it offers a lump sum the choice is a planning decision, not an investment one. Lump sum or monthly.
Here, yes. Most people have put it off, and it's done in concert with the rest because the same decisions are involved.
Tax advisory, tax planning implementation, and tax preparation are provided through Talley Tax, a separate business owned and operated by David Talley. Tax advice is given by Talley Tax. Talley Wealth and Talley Tax work in concert, and they are separate entities. Securities and advisory services are offered through Cambridge entities as described in the site footer; Talley Tax is not affiliated with Cambridge. Talley Wealth advisory services do not include tax preparation unless a separate Talley Tax relationship is established. About Tax Advisory.
The next conversation
Gather the most recent statement for each account, your latest Social Security estimate, and a rough sense of what a year of your life costs. Then the first step is an Explore Call, fifteen minutes by phone, with the question that's on your mind.
Our office is in Johnson City, and we work with families in Kingsport, Bristol, Greeneville, Abingdon, and the towns around them.